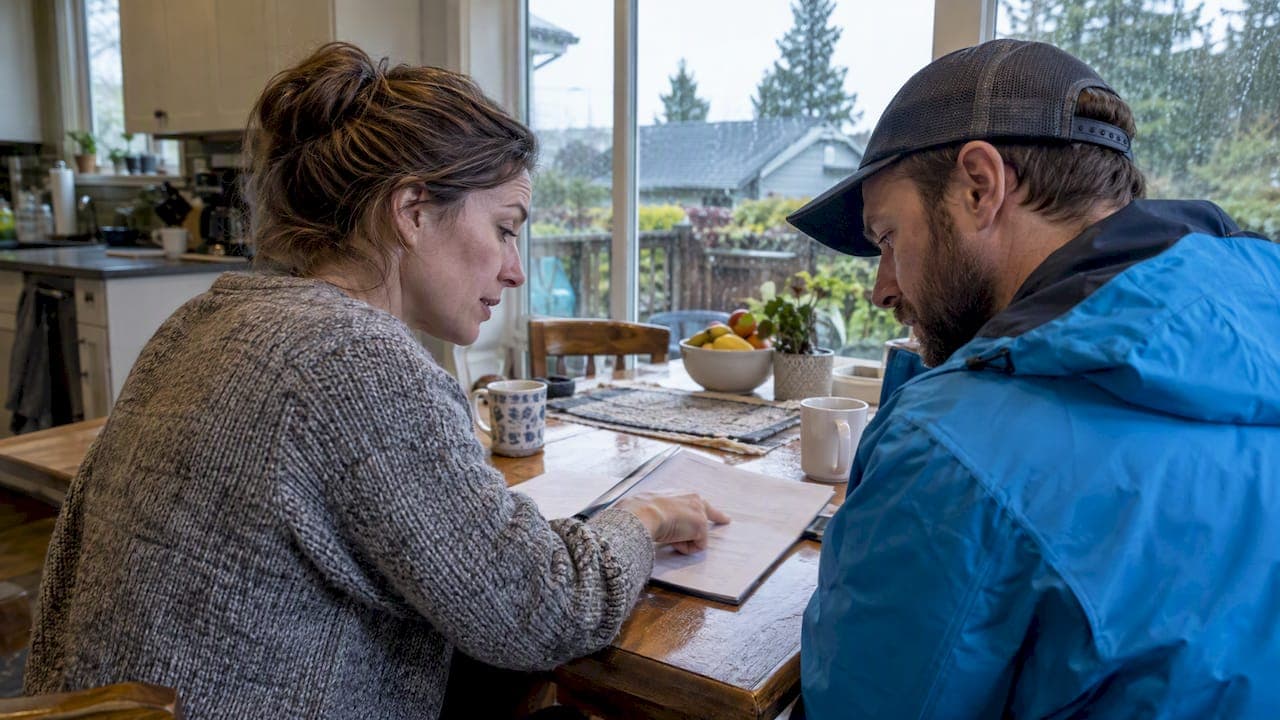
Yes, always hire an insured contractor. It limits your financial and legal exposure if something goes wrong on your property, from a worker injury to accidental damage. Before any work begins, ask for two documents: a certificate of insurance and, where applicable, a workers' compensation clearance letter. Both take minutes to request and can save you thousands.
TL;DR:
- Verify that the contractor has commercial general liability insurance with coverage limits appropriate for your project's size.
- Confirm the contractor and subcontractors carry workers' compensation coverage by requesting a clearance letter before work begins.
- Ensure you notify your home insurer about the renovation and confirm that your homeowner policy covers the specific scope of work.
- Watch for red flags such as no written contract, refusal to provide proof of insurance, or quotes significantly lower than other estimates.
- Understand that a certificate of insurance confirms coverage at a point in time but does not guarantee continuous protection or quality of work.
Table of Contents
- Why contractor insurance matters: the concrete risks it prevents
- Types of contractor insurance homeowners should ask about
- How contractor insurance works with your homeowner policy
- How to verify insurance: a step-by-step homeowner checklist before work starts
- Red flags and common mistakes that increase homeowner risk
- Publisher perspective: what responsible, insured service looks like
- Legal requirements and regulations for contractor insurance
- Case studies or examples illustrating the risks of hiring uninsured contractors
- What the checklist culture gets wrong about contractor insurance
- If you need insured exterior cleaning or maintenance
- FAQ
- Sources
Why contractor insurance matters: the concrete risks it prevents
When a contractor works on your property, you are exposed to risks you may not think about until something happens. A worker gets hurt on your roof. A pressure washer cracks a window. A subcontractor backs a truck into your fence. Insurance is what stands between those moments and your bank account.
The biggest risk for homeowners is liability for third-party injuries and property damage that happen during the job. If an uninsured contractor's worker is hurt on your property, you could be drawn into a claim or lawsuit with no commercial policy to absorb it. In some provinces, hiring a contractor who is not keeping up with required workers' compensation payments can even make the homeowner responsible for those unpaid premiums.
Here is what insurance is actually protecting against:
- Injury claims from workers hurt on your property
- Accidental damage to your home, landscaping or neighbouring properties
- Unpaid workers' compensation premiums that could otherwise fall back on you
- Defects or incomplete work left unresolved after a dispute
Insurance is one control among several. A contract that spells out the scope of work, proper permits and a final inspection matter just as much.
Types of contractor insurance homeowners should ask about
Not all contractor insurance is the same, and knowing the basic categories helps you ask sharper questions; for details on contractor roles and why insurance matters, see what a full-service contractor actually does in Canada.
- Commercial general liability (CGL): covers third-party injury and property damage claims; ask what the policy limit is and whether it fits the size of your project.
- Workers' compensation coverage: confirms the contractor's workers are covered if hurt on the job; a clearance letter is the document that proves this.
- Automobile liability: relevant when contractor vehicles, trailers or equipment are parked or operating on your property.
- Completed operations and pollution liability: cover problems that surface after the job is done, including environmental issues from materials or runoff.
- Umbrella or excess coverage: adds a layer above standard limits for larger, higher-risk jobs like major renovations or commercial buildings.
Sample federal procurement insurance schedules show commercial general liability limits commonly set within a range appropriate to contract size, which illustrates how coverage limits scale with project risk rather than being a fixed number for every job. A small gutter cleaning does not need the same limit as a full exterior rebuild. If you are unsure what limit fits your project, ask the contractor's broker directly.
How contractor insurance works with your homeowner policy
Your home insurance is not a substitute for a contractor's commercial coverage. The two work side by side, and the gap between them is where homeowners get caught off guard.
Tell your insurer before renovation work starts. Undisclosed work can complicate a claim later, and your policy's terms determine what is actually covered during a renovation, not a general assumption of protection. Financial Consumer Agency of Canada guidance treats home insurance as complementary, not a replacement for commercial liability.
A few scenarios where homeowners stay exposed even with insurance in place: acting as the prime contractor on your own renovation, hiring an owner-operator who has personally declined workers' compensation coverage, or assuming a verbal "yes, we're insured" means every worker on site is covered.
Pro Tip: Call your home insurer the same week you sign a renovation contract, not after the work is already underway.
How to verify insurance: a step-by-step homeowner checklist before work starts
Verifying coverage takes a short phone call or email, and it is worth doing before you sign anything.
- Ask for a certificate of insurance (COI) showing the insurer's name, policy number and coverage limits.
- Request a workers' compensation clearance letter confirming the contractor and any subcontractors are in good standing.
- Confirm business registration and any required permits for the scope of work.
- Get a written contract before paying a deposit or starting work.
- Check the COI for an additional insured endorsement naming you, along with effective and expiry dates and a notice of cancellation clause.
Consumer guidance from Canada's Office of Consumer Affairs recommends asking contractors directly about liability insurance and workers' compensation, and putting the full scope of work in writing.
Your written contract should cover:
- Scope of work and materials to be used
- Payment schedule tied to milestones, not a lump sum upfront
- Whether subcontractors will be used and who insures them
- Permits, inspections and who is responsible for arranging them
- Warranty terms and how disputes will be resolved
Red flags and common mistakes that increase homeowner risk
Some warning signs show up before a single tool touches your property.
- Insisting on cash only, with no invoice or paper trail
- Refusing to provide a COI or clearance letter when asked
- Starting work without pulling required permits
- Offering no written contract, just a verbal agreement
- Quoting a price well below every other estimate you received
The consequences of ignoring these signs range from a voided warranty to a denied insurance claim and repair costs you cover yourself. If you discover mid-project that a contractor is not actually insured, stop work, get everything in writing from that point forward, and contact your own insurer before proceeding further.
Publisher perspective: what responsible, insured service looks like
A good benchmark for what proof of coverage should look like comes from how established local providers operate. Island Moss Busters is family run, fully insured, and uses eco-friendly cleaning methods across two crews, backing its roof cleaning work with a written two to two-and-a-half year moss return guarantee.
That combination, a real insurance policy, a documented scope of work and a written guarantee, is what homeowners should expect from any exterior maintenance provider, not just one doing roof work. It is also what protects resale value: a roof or exterior cleaned by an insured provider with paperwork on file is one less question for a buyer's inspector or a listing agent to raise later.
Legal requirements and regulations for contractor insurance
Insurance requirements for contractors are not set by one single rule across the country. Workers' compensation coverage is generally administered province by province, and the obligations attached to hiring a contractor, including whether a homeowner can be held liable for unpaid premiums, depend on that province's scheme. WorkSafeBC's guidance for homeowners is one example of how a provincial workers' compensation board frames this responsibility, and similar bodies exist in other provinces under different names.
Beyond workers' compensation, municipalities typically set their own permit and licensing rules, and some trades carry additional licensing requirements on top of general contracting rules. There is no single national contractor insurance law that applies uniformly everywhere, which is exactly why asking for documentation specific to your province and municipality matters more than assuming a contractor is covered because they are covered somewhere else.
For larger commercial or multi-trade projects, insurance requirements often scale with contract value and risk, similar to the tiered limits seen in federal procurement schedules. Homeowners taking on a renovation that involves multiple trades should ask whether each trade carries its own clearance and liability coverage, since a clearance letter for one trade does not cover another working on the same job.

Case studies or examples illustrating the risks of hiring uninsured contractors
The clearest way to understand the risk is to walk through what typically goes wrong.
Consider a homeowner who hires a contractor directly, skipping a general contractor, to manage a roof replacement. If that homeowner is acting as the prime contractor and the hired worker is injured, the homeowner can face direct exposure to workers' compensation obligations rather than the contractor absorbing that risk. WorkSafeBC's guidance on who needs coverage exists specifically because this scenario is common enough to warrant a dedicated page.
Another frequent pattern: a contractor says they are "insured," but that coverage only applies to employees, not to the owner or partners running the business. If that owner is injured on your property and has personally declined coverage, you may be the one facing a claim. This is why WorkSafeBC's contractor classification guidance specifically flags proprietor coverage as something homeowners need to confirm, not assume.
A third pattern shows up with multi-trade renovations. A homeowner confirms the general contractor's coverage but never checks the electrician or plumber working under them. If that subcontractor is not separately covered, the protection the homeowner thought they had does not extend to that part of the job. None of these situations require an unusual contractor or a rare mistake. They happen when a homeowner takes a verbal assurance at face value instead of asking for paper.

What the checklist culture gets wrong about contractor insurance
Most homeowner guides treat insurance verification like a box to check once, early in the process, then forget. That misses the point. A certificate of insurance is a snapshot, not a guarantee that covers every day of a multi-week project, and a policy can lapse or exclude a specific trade without you knowing.
The bigger blind spot is proprietor coverage. Homeowners fixate on whether a company "has insurance" and rarely ask whether the actual person on their roof is covered as an employee or has declined coverage as an owner. That single question catches more real exposure than checking a policy number ever will.
If you take one thing from all of this, prioritize asking who specifically is covered, not just whether coverage exists. A clearance letter confirms a company's standing, not individual workmanship or safety practices, so pair it with references and a clear written contract. Paperwork protects you only when you actually read what it says.
— Island
If you need insured exterior cleaning or maintenance
If this has you thinking about your own roof, gutters or siding before the wet months set in, that is exactly the kind of project where insurance verification matters most. Island Moss Busters is fully insured and family run, and we provide written quotes and guarantees so you know what you are getting before work starts.
Our services include:
- Roof cleaning and moss removal, backed by a two to two-and-a-half year moss return guarantee
- Gutter cleaning and gutter guard installation
- House washing and pressure washing for driveways and exteriors
- Window cleaning and permanent Christmas light installation
Ask us for proof of insurance and clearance documentation before booking, the same way you would with any contractor. Request a quote on our roof cleaning page and we will walk you through the paperwork alongside the work itself.
FAQ
Why are insurance contracts important for homeowners?
An insurance contract sets out exactly what a contractor's policy covers and for how much, so you know what protection you actually have before work begins. Without it in writing, you are relying on a verbal promise that may not match what the policy says. Reviewing the certificate of insurance is the only way to confirm the terms match your project.
What are the main elements of a contractor's insurance contract?
A contractor's certificate of insurance typically lists the insurer's name, policy number, coverage limits, effective and expiry dates, and any endorsements such as naming you as an additional insured. It should also include a notice of cancellation clause so you are told if coverage lapses. These elements let you confirm the policy is active and sized for your job.
What insurance should contractors have before starting residential work?
At a minimum, contractors should carry commercial general liability insurance and valid workers' compensation coverage for every worker on site, including subcontractors. Larger or higher-risk projects may also call for automobile liability, completed operations or umbrella coverage. Ask for a clearance letter to confirm standing rather than relying on a verbal assurance.
What are the two main types of contractors homeowners hire?
Homeowners generally hire either a general contractor, who manages the full project and subcontractors, or specialty trade contractors hired directly for one scope of work, such as roofing or gutter cleaning. Each type carries its own insurance obligations, and hiring trades directly means you are responsible for confirming each one's coverage separately. This distinction matters most on multi-trade renovations where no single party is managing the paperwork for you.
Does a clearance letter guarantee good workmanship?
No, a clearance letter only confirms a contractor is registered and up to date on required premium payments. It says nothing about the quality of their work or their safety record on site, according to WorkSafeBC's own guidance. Pair it with references, a written contract and permit checks for a complete picture.
Sources
- Home renovations (Office of Consumer Affairs, Innovation, Science and Economic Development Canada)
- Home insurance (Financial Consumer Agency of Canada)
- Homeowners — Who needs coverage? (WorkSafeBC)
- Annex G — Insurance requirements (CanadaBuys sample)